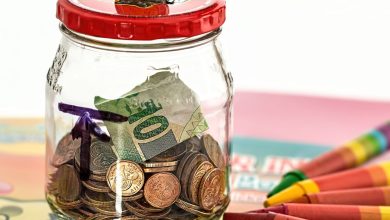

Some household costs are predictable in everything except their timing in a monthly budget: car insurance renewals, annual service charges, school trips, boiler repairs and festive spending all arrive regularly, yet they often feel like emergencies when they land. Money advisers say more households are responding with sinking funds, which are small, named pots of money built up month by month for a specific future cost. Instead of paying a large annual bill from one month of income, the household divides the expected cost by twelve and saves that amount steadily, so the bill is already funded when it arrives. The method works because it replaces guesswork with a list, and each pot has a clear purpose that makes it easier to leave untouched. Families often start with only two or three categories, such as car costs and home repairs, before adding others once the routine feels normal. Keeping the pots visible in a banking app or a simple notebook also helps everyone in the household understand where spare money is already committed. Over time, the approach reduces reliance on credit for ordinary, foreseeable expenses and makes monthly budgets feel calmer and far more honest.
What the Evidence Shows
Advisers recommend reviewing each pot twice a year, because insurance premiums, energy costs and repair prices change, and a fund based on last year may fall quietly short. If a pot grows larger than needed, the surplus can be moved deliberately rather than spent by accident, while a shortfall can be topped up gradually instead of in a panic. Households should keep sinking funds separate from a general emergency fund, which exists for genuinely unexpected events such as job loss or a broken essential appliance. Naming each pot clearly, setting the transfer for just after payday and checking balances during a monthly review all help the system survive busy periods. Even modest pots change how a bill feels when it arrives, turning a demand for payment into a simple transfer from money that was saved for exactly that purpose throughout the year. Starting small keeps the habit realistic for tighter budgets as well. Reporting and analysis from sources such as International Monetary Fund track the same developments, and specialists following household sinking funds planning say the direction is now consistent across independent lines of evidence.
The Wider Context
The wider context is a financial system repricing risk after a long era of cheap money. Decisions shaped by household sinking funds planning are being made under closer supervisory attention, with stress tests and disclosure rules that assume conditions can worsen quickly. Institutions that planned for the benign case are adjusting in public, which is uncomfortable and healthy in equal measure.
What Happens Next
What happens next with household sinking funds planning will be visible first in the data that professionals watch weekly: flows, spreads and the terms on new deals. Participants who spoke for this article expect a period of adjustment rather than drama, with the biggest effects landing on those who assumed the old conditions were permanent. Planning, as ever, is the cheapest hedge. You can follow related developments in our coverage of finance.
There is a practical lesson in all of this for readers deciding what to do today. Start with the verified facts, be wary of anyone promising certainty, and prefer reversible steps while the evidence is still developing. Circumstances differ by country, income and personal situation, so general guidance should always be weighed against your own context before you act on it in any significant or lasting way.